Christine Lagarde says ECB rate rises are not the main cause of Europe's housing crisis. She points to a gap between housing supply and demand, while acknowledging higher mortgage costs, weak investment and a severe shortage of homes in countries such as Spain.
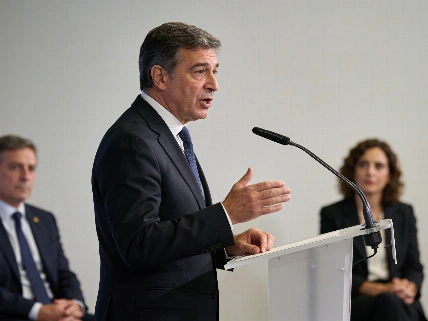
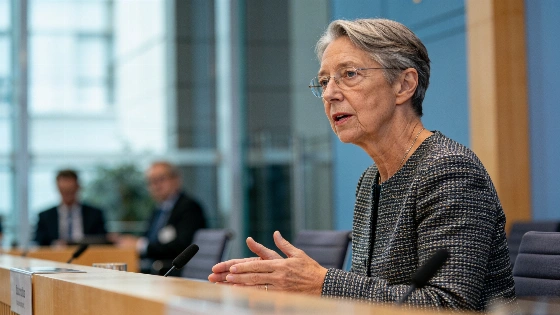
On 28 September, Christine Lagarde told the European Parliament's Economic and Monetary Affairs Committee that Europe's housing crisis is rooted mainly in a gap between supply and demand. The ECB president spoke in Brussels as lawmakers examined how monetary policy affects households looking for a stable home.
Her argument does not dismiss the cost of borrowing. Higher rates make mortgages more expensive. Lagarde said ECB decisions eventually pass through to financing costs, but she rejected the idea that this explains the wider crisis on its own.
The ECB raised its three key interest rates by 25 basis points on 10 September 2026. The deposit rate reached 2.50%. The refinancing rate rose to 2.65%, and the marginal lending rate reached 2.90%.
On 10 September 2026, the ECB raised all three key interest rates by 25 basis points. The deposit rate rose to 2.50%, while the refinancing and marginal lending rates reached 2.65% and 2.90% respectively.
Lagarde also spoke about the human cost. She said she felt sad when people lost their homes. In recent days, she had paid particular attention to events in Spain. Her point was broader than one country. She described housing as a central concern for people across Europe.
The latest rate decision provides one specific measure. Lagarde said the 25-basis-point increase adopted in June had lifted household mortgage costs by 0.01%, based on the ECB's observations. She presented that figure as a sign that the immediate effect of the latest move was small compared with the supply problem.
Rates still matter. Monetary tightening can raise the cost of finance and make it harder for households to buy or keep a home. Lower borrowing costs alone would not create the missing homes or fix the imbalance across many European countries.
The official ECB account also said longer-term interest rates had risen noticeably. They were expected to restrain growth and inflation more than the September forecast had projected. Financial conditions are tighter.
The housing shortage in Spain is estimated at roughly 700,000 to 755,000 homes. Spanish assessments cited by AFP and local reporting warn that the accumulated deficit could grow by a further 300,000 homes in 2026–2028 if construction does not catch up with demand.
Euro-area data show why construction remains central to the debate. Housing investment fell by 1.3% quarter on quarter in the second quarter of 2026, after a 1.9% decline in the previous quarter. The ECB expects a gradual recovery, but the recent figures show that tighter financial conditions are weighing on building activity.
Spain has seen the problem become a major social and political issue. Bank of Spain estimates put the shortage at around 700,000 homes. Other Spanish assessments put the accumulated deficit at 755,000 units.
Large demonstrations in Madrid called for stronger tenant protection and a ban on evictions without alternative accommodation. The protests show why Lagarde linked monetary policy with the loss of homes and growing housing insecurity.
The Bank of Spain has described the housing problem as a serious economic and social challenge. So far, it has not identified the issue as a threat to financial-system stability. That distinction allows central banks to discuss housing affordability as a major public concern without calling it a banking crisis.
The main risks instead lie in weak construction, limited supply and the continuing gap between demand and available homes. Officials had no quick fix.
Two facts can be true at once. Higher rates can raise mortgage costs for households. The wider housing crisis can still come mainly from problems that interest rates cannot solve.
Reuters reported that Lagarde still considered measured ECB rate increases appropriate for controlling inflation. The central bank's own material also acknowledged that higher long-term yields were already tightening financial conditions. Her position puts the main weight on the supply problem without denying the financial pressure caused by rates.
The clearest reading of her statement is not that ECB policy has no effect on housing. It is that the central bank does not see its latest rate increases as the main explanation for the crisis. For households in Spain and elsewhere in Europe, mortgage costs remain part of the burden. Finding an affordable and secure home still depends on a supply-and-demand problem that the ECB cannot settle through interest rates alone.