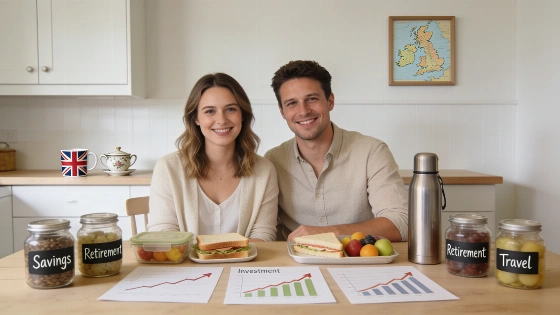
Alan and Katie Donegan, who left their jobs at 35 and 40, had built a net worth of £1 million before either turned 41. As BBC News reported, a decade of radical saving and disciplined investing laid the groundwork for their early retirement. Living in southern England, they made deliberate choices, including preparing every lunch at home. Alan said the habit saved them $53,000 over ten years. That works out to about $5,300 a year, or $442 a month.
Packed lunches were only the beginning. During cold months, they avoided turning on the heating, layering up and using hot-water bottles instead. They charged their phones outside the house and hunted for discount coupons, while rarely ordering main point. Friends sometimes questioned their extreme frugality, but for Alan and Katie, every cutback brought financial independence closer.
From High Earners to Early Retirees
Alan started as a landscaper before launching a personal development business, while Katie worked as an actuary at a financial firm. Both earned solid incomes, allowing them to save aggressively and channel nearly all surplus funds into investments. When their assets reached £1 million, about $1.3 million at the conversion used in the coverage, they decided it was time to leave the workforce. The key stage reflects how their finances came together, with packed-lunch savings one part of a broader strategy.
The FIRE Movement: Promise and Reality
The Donegans’ approach is rooted in the FIRE movement, or Financial Independence, Retire Early. Followers aim to build enough wealth to cover living expenses without relying on a salary. A common benchmark is to accumulate 25 times annual spending, then withdraw roughly 4% of the portfolio in the first year. For example, 4% of £1 million is £40,000. The 4% rule is a planning heuristic, not a guarantee. Its historical basis includes William Bengen’s 1994 research and the 1998 Trinity study, which examined historical investment returns over finite retirement periods.
Retirement length matters. People leaving work in their 30s may need their money to last five decades or longer, well beyond the conventional 30-year horizon. Recent Morningstar modelling cited in retirement-planning guidance puts sustainable initial withdrawal rates around 3.7% to 3.9% for 30 years, about 3.1% to 3.3% for 40 years and roughly 2.9% for 50 years, depending on the assumptions. These are modelled estimates, not universal safe rates. They depend on assumptions about portfolio mix and fees, the effects of inflation and taxes, and whether retirees can adjust spending.
Not everyone pursues FIRE with such intensity. Some choose “Barista FIRE,” combining investment income with part-time work to reduce the savings target. Earned income can lower portfolio withdrawals, particularly during market downturns. Others take a different route. American educator Amy Minkley worked at international schools across Asia, shared housing and went without a car. She retired at 44 and relocated to Bali, where the cost of living was lower.
Barriers and Cautions
Financial experts caution that early retirement is out of reach for many, especially as housing and everyday costs rise alongside debt levels. Some FIRE principles, such as starting to save young and increasing retirement contributions after each raise, can benefit many. The strictest versions, but, demand high incomes and unwavering discipline, as well as the ability to weather unexpected setbacks without returning to work. In the UK, Department for Work and Pensions figures cited in recent coverage show the share of 22- to 29-year-olds opting out of workplace pensions rising from 6.6% in December 2020 to 11.5% in December 2025. Pensions UK estimates cited in the same coverage put the annual income associated with a “comfortable” retirement at £45,400 for one person and £62,700 for a couple. Those figures show how much a retirement target depends on household spending and circumstances.
There are personal trade-offs, too. Years of austerity can affect well-being, straining health and relationships. In Spain, retiring on private savings at 35 or 40 is rare. Information from Social Security data, the average age for early retirement remains over 63.
The Donegans are not the only ones to choose an unconventional retirement. Jane Post, for instance, found a new sense of freedom by moving into a tiny home in her daughter’s Florida garden after decades in a larger house. Her approach to reshaping retirement was different, but just as personal, as described in this account of downsizing later in life.