Most of the 129 brands competing for buyers in China’s electric-car industry are expected to disappear by 2030. The shakeout is underway, and few are likely to survive.
The numbers show the scale of the competition. By the end of 2025, China had more than a hundred EV brands on the market. AlixPartners says about 15 groups will take most of the profits in the next few years. BYD and Li Auto are among the rare winners making money; the rest are caught in a price war, with razor-thin margins and widespread overcapacity. Official Chinese sources acknowledge the problem. The government plans to establish early warning systems for excess capacity and tighten entry requirements for new makers, while pushing industry restructuring between 2026 and 2030.
“By May 2026, 23 Chinese EV manufacturers had declared bankruptcy or ceased operations, leaving around 850,000 vehicles without guaranteed service, software updates, or spare parts,” said the China Automobile Dealers Association.
These are not failed startups. Many are established companies with global ambitions, now fighting to stay alive as growth slows. BYD started a wave of price cuts in 2023, followed by rivals including Nio, Xpeng, Leapmotor and Zeekr. Even Tesla joined in from its Shanghai plant. More cars were sold, but less money was made; some companies lose money on every car. Regulators have begun cracking down on loss-making sales, monitoring discounts and dealer targets that eat into profits and threaten suppliers, information from several industry sources.
China’s factories can build far more cars than buyers need, setting the stage for trouble. When supply outpaces demand, consolidation follows. The industry calls it 内卷 (“neijuan”): everyone works harder, invests more and cuts prices, while profits vanish and the list of casualties grows. Aiways faded from Europe. Jiyue, backed by Geely and Baidu, collapsed in late 2024, leaving customers in limbo. WM Motor went bankrupt, HiPhi stopped operations, and Evergrande Auto became a warning to others. Yet new brands keep appearing as old ones disappear. Sector data shows the average brand in China sells about 80,000 cars a year, far below the 400,000 units needed to break even.
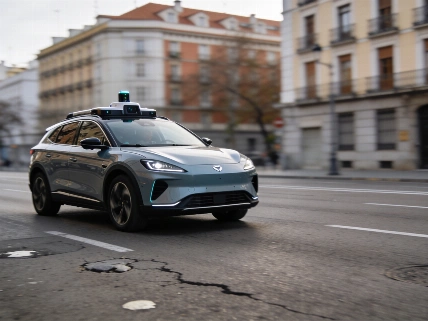
From the outside, Chinese carmakers may look like a single force. Inside, the market is chaotic and splitting apart. As competition at home intensifies, Europe is the next target. MG, BYD, Omoda, Jaecoo, Leapmotor, Xpeng, Lynk & Co and Zeekr have all arrived in Spain, joining more than 90 brands selling passenger cars. The question is how many will last.
“The Chinese government’s official plan aims to raise the share of new energy vehicles to 70% of passenger car sales by 2030, while reducing redundant capacity and inefficient enterprises. Authorities are also tightening controls on local subsidies and price competition to avoid repeating the overcapacity crises seen in the solar and steel industries,” information from the official Chinese government plan.
Many Chinese brands now need overseas sales to survive at home. Their push into Europe is less a conventional expansion than a scramble for new markets to ease the pressure. That is why they move quickly and cut prices sharply. Some European makers are adapting: Stellantis will build Leapmotor models in Zaragoza and Madrid, while Volkswagen is open to joint production with Chinese partners to keep its European plants busy. Renault is working on urban EVs with Chinese technology. CATL has exported its whole platform to Togg for the first time. The line between European brands and Chinese technology is fading. As reported earlier, Spain is now a basic base for Chinese automakers in Europe.
Japan and South Korea went through similar shakeouts, but more slowly and on a smaller scale. In the 1950s and 60s, Japan had dozens of small carmakers. Most vanished, merged or were absorbed; only giants such as Toyota, Honda, Nissan, Mazda and Mitsubishi survived. Korea saw the same pattern, with Hyundai-Kia becoming the basic group. China is heading in the same direction, but at a faster pace and on a much larger scale. The world is switching to electric cars, while Europe is losing its lead in combustion engines.
For European buyers, the influx of Chinese brands may seem new or exotic. In reality, China is deep into a harsh phase of consolidation. The risk for buyers is choosing among more brands while trying to guess which ones will still be around in five or ten years. When a brand dies, its warranties and support can go too, along with spare parts and software updates. Some early Chinese brands in Europe have already left customers stranded. In the electric age, batteries and software matter more than engines. Confidence that a maker will survive for a decade is now a basic part of a car’s value.
This is a major shift in who runs the global car industry, well beyond a wave of cheap imports. The most valuable parts of an electric car, including batteries, materials refining, power electronics and much of the software, are already centered in Asia, especially China. While Europe debates tariffs and subsidies, China is deciding which companies will survive the most brutal selection the car industry has ever seen. Most will not make it. The few that do will be stronger, leaner and more global than the Chinese brands Europeans remember from five years ago. By 2030, many cars on European roads will be a direct or indirect result of this upheaval.