JPMorgan is preparing a possible sale of Parques Reunidos for EQT, in a transaction that could value the group at around €1.7 billion. The process is still at an early stage and may attract industrial operators such as Merlin Entertainments and Compagnie des Alpes. The move puts the owner of Parque de Atracciones de Madrid and Parque Warner back under review.
Several market sources consulted by EXPANSIÓN provided the information. EQT and JPMorgan declined to comment. The potential buyer list remains open as the financial adviser prepares the sale.
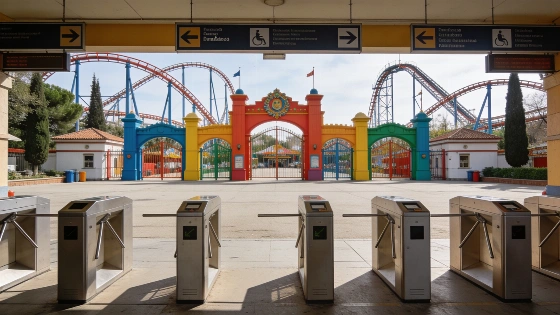
The Ayuntamiento de Madrid's tender documentation requires the operator of Parque de Atracciones de Madrid to commit €15 million in investments during the first three years of the concession. In 2026, Madrid's city authorities sought a new operator for the park, which Parques Reunidos currently runs. The tender terms included an annual €400,000 fee and a variable payment equal to 8% of revenue, Infobae reported.
Parques Reunidos is Spain's leading amusement park operator.
The group is based in Madrid and runs more than 30 leisure centres in ten countries. Its portfolio includes Parque de Atracciones de Madrid, Parque Warner, Zoo Aquarium, Faunia, Atlantis Aquarium, several Aquópolis sites, Movie Park Germany, Tropical Islands, Mirabilandia, Bobbejaanland, Slagharen and TusenFryd.
Parques Reunidos earns revenue from admission fees and season passes, along with restaurants, shops, merchandising, additional services and accommodation at some complexes.
The group now operates in nine European countries and Australia. After selling its United States business to Herschend, it generates around €530 million in annual revenue and has EBITDA above €170 million, information from the sources. The United States had been its biggest market, accounting for close to 35% of total revenue.
EQT took control in 2019 through a public tender offer launched by Piolin BidCo. Corporación Financiera Alba and Belgian holding company Groupe Bruxelles Lambert also joined the vehicle. EQT now owns 52% of Parques Reunidos, Alba owns 25% and GBL owns 23%.
When EQT entered, the company had an enterprise value of €2.085 billion. The Swedish investment manager allocated 6% of EQT Infrastructure IV to the acquisition. The fund raised €9 billion in 2019. EQT invested around €540 million of capital in the Spanish company before any possible co-investments.
The shareholders have already taken some gains through asset sales. Early last year, Parques Reunidos agreed to sell its United States operations to Herschend for around €1 billion. It also agreed to sell Belantis in Germany to Compagnie des Alpes for approximately €22 million.
After the US disposal, the group refinanced its remaining debt on more favourable terms and paid a dividend to shareholders.
The latest operating figures show a smaller group with lower costs. Revenue reached €550 million in 2025, down 4.7% on a comparable basis. Higher visitor spending partly offset slightly lower attendance. Reported revenue fell 36% because of the US sale, while operating costs dropped 11%, a faster decline than sales.
Spain generated €196 million in revenue and Germany €172 million. Italy contributed €49 million, the Netherlands €33 million, Belgium €27 million and Norway €26 million. Spain and Germany accounted for roughly two-thirds of group sales. Capital expenditure stood at €62 million in 2025, 22% below the comparable figure.
Parques Reunidos has sold assets and refinanced its debt, while narrowing its geographic focus ahead of a possible sale. That leaves JPMorgan with a smaller, more focused leisure group to present to potential industrial buyers.
The sale is still being prepared and has not been agreed. The €1.7 billion valuation gives the market a measure of what EQT is testing. Madrid is also reviewing the operating terms for a major park, an issue that may affect how bidders assess the group's Spanish assets, information from tender information reported by Infobae.