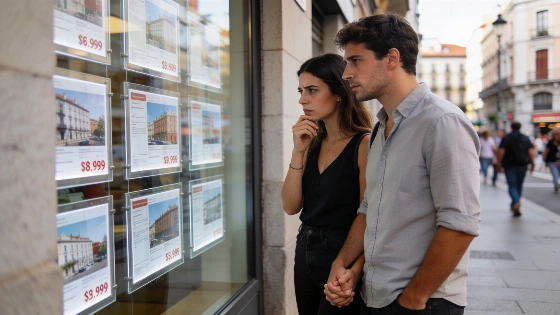
Buying a home in Spain now demands sharply different incomes depending on where you live. In Madrid, Barcelona, and San Sebastián, the required net salary is more than double the national average, while smaller cities remain far more accessible. A new study reveals the numbers behind Spain’s housing divide.
Securing a home in Spain has become a test of income—and geography. According to a recent study by Accumin Intelligence, the average net monthly salary needed to buy a typical home without exceeding a 35% mortgage burden is now €1,999. But this figure hides a dramatic divide: in Madrid, Barcelona, and San Sebastián, the required income soars well above €4,000, reshaping the reality of who can afford to buy.
San Sebastián tops the list, demanding a net monthly income of €5,074 to purchase a standard 100-square-meter property. Madrid follows at €4,574, with Barcelona close behind at €4,485. These three cities stand alone in requiring more than double the national average, reflecting the relentless pressure of urban housing markets.
Outside these hotspots, the numbers remain daunting. In Getafe, buyers need €2,950 net per month; in L’Hospitalet de Llobregat, €2,896; and in Badalona, €2,705. Marbella, Palma de Mallorca, and Bilbao all exceed €3,000. Even in Valencia and Seville, the threshold is set at €2,675 and €2,566 respectively. Fourteen of the sixty cities analyzed now require more than €2,500 net per month to buy a home under the study’s criteria.
Yet the contrast with Spain’s less pressured markets is striking. In Zamora, a net monthly income of just €1,279 is enough, nearly four times less than in San Sebastián. Lugo, Ciudad Real, and Palencia all fall below €1,350. Along the coast, Benidorm requires €2,813, but Castellón drops to €1,338. Murcia and Almería remain among the most accessible, at €1,526 and €1,727 respectively. For many, looking beyond the major cities is the only realistic path to homeownership.
Accumin’s calculations are based on a standard scenario: a 100-square-meter home, an 80% mortgage, and a French amortization system, with the monthly payment capped at 35% of net income. This mirrors the lending criteria used by Spanish banks, which rarely finance more than 80% of a property’s value and typically set the debt-to-income ceiling at 30–35%. Buyers must also cover the down payment, taxes, and transaction costs from their own savings.
Recent data from Spain’s National Statistics Institute (INE) underscores the challenge. In May 2026, 42,213 new mortgages were signed, with an average loan amount of €174,866—up nearly 10% year-on-year. The average interest rate for new loans stood at 2.98%. These figures highlight how rising prices and stricter lending standards are reshaping the market.
The gap between cities is not just a matter of statistics—it shapes real lives. As housing costs outpace salaries in major urban centers, more young professionals are forced to reconsider their options. For example, the story of Ana Ramos, a 25-year-old who returned to her parents’ home after rent became unaffordable, illustrates how even stable employment no longer guarantees independence in Spain’s most expensive cities.
It’s important to note that the required salary calculated by Accumin only covers the mortgage payment, not the full cost of buying a home. Prospective buyers still need significant savings for the down payment and additional expenses. The study’s figures offer a clear comparison between cities, but the true barrier to homeownership is often even higher.
For those considering a move, the message is clear: where you live in Spain now determines not just your lifestyle, but your financial future. As the housing divide widens, the decision between city life and affordability has never been starker.