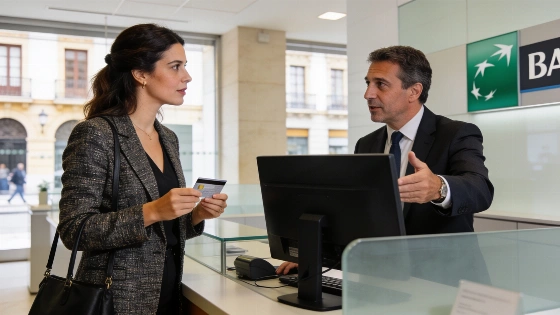
Spanish banks can still raise credit card limits without explicit customer consent, as the government’s proposed law remains in draft form. The EU’s November 2026 deadline looms, but for now, unilateral credit increases are not yet prohibited.
Spanish consumers hoping for tighter controls on unsolicited credit card limit increases will have to wait. The government’s much-discussed ban on raising card limits without a customer’s explicit request is not yet in force, as the proposed legislation remains at the draft stage.
The Council of Ministers approved the draft Law on Consumer Credit Contracts on January 7, 2026, but it has not yet been enacted. According to official sources consulted on August 31, the text is still classified as a draft. If passed, the law would require banks to obtain a clear, affirmative request and explicit consent from customers before granting any new credit or increasing existing card limits. The law would take effect twenty days after its publication in the Official State Gazette.
What the Law Would Change
The draft’s Article 63 is direct: “Any granting of credit to consumers that has not been previously requested and without their express consent is prohibited.” This rule would apply to all forms of consumer credit, not just physical cards. It would also prevent banks from making more credit available to clients without a prior request, regardless of the product’s commercial name.
Currently, sending an unsolicited card is already restricted except for certain replacements. However, banks can still unilaterally increase credit limits. Under the new law, such increases would require a customer’s explicit request and consent. Automatic activation of new credit lines or overdrafts would also be banned. Pre-approved credit offers could still be advertised, but not activated without customer authorization.
EU Directive and Broader Impact
The European Directive (EU) 2023/2225 aims to prevent unsolicited pre-approved cards, new overdraft facilities, and unilateral limit increases. As a result, automatic credit limit hikes would need to be requested and expressly accepted by the consumer. While having more available credit does not force spending, it can increase potential debt and influence future financial decisions.
The proposed Spanish law would also introduce a temporary 22% interest cap on new consumer credit operations, including revolving cards, until further regulations are developed. It would extend to microloans, quick loans, and “buy now, pay later” schemes. All consumer credit lenders would need authorization and supervision from the Bank of Spain, including digital operators and new financial entities. Retailers offering direct financing would have to provide interest-free payment plans, while any paid financing would need to go through a regulated entity. Contracts from unauthorized lenders would be considered void.
When Will the Ban Take Effect?
The draft law envisions a general start date twenty days after publication in the BOE, with cost limitation rules following three months later. Some obligations for high-cost lenders would be delayed up to twelve months. The EU requires Spain to transpose the directive by November 20, 2025, and to apply national measures from November 20, 2026. However, these EU dates do not automatically make the Spanish draft law effective.
Until the law is officially enacted, Spanish banks can continue to offer and even increase credit limits without prior customer approval. Consumers should remain vigilant: if they receive an unsolicited card, the Bank of Spain recommends declining it at the branch or contacting customer service, and keeping a record of the communication. If the issue persists, a formal complaint should be filed with the bank, and if unresolved, escalated to the Bank of Spain.
Spain’s approach to implementing EU consumer protection rules echoes delays seen in other sectors. For example, as noted by russpain.com, major retailers have also postponed compliance with new EU deposit schemes for beverage containers, highlighting the broader challenge of aligning national practices with European regulations. One recent case involved a leading supermarket chain delaying the introduction of a bottle deposit system despite looming EU deadlines.
For now, Spanish consumers should be aware that the much-anticipated ban on unsolicited credit limit increases is not yet law. The coming months will determine how quickly these protections become reality—and how banks and lenders adapt to the new regulatory landscape.